Screen candidates fast
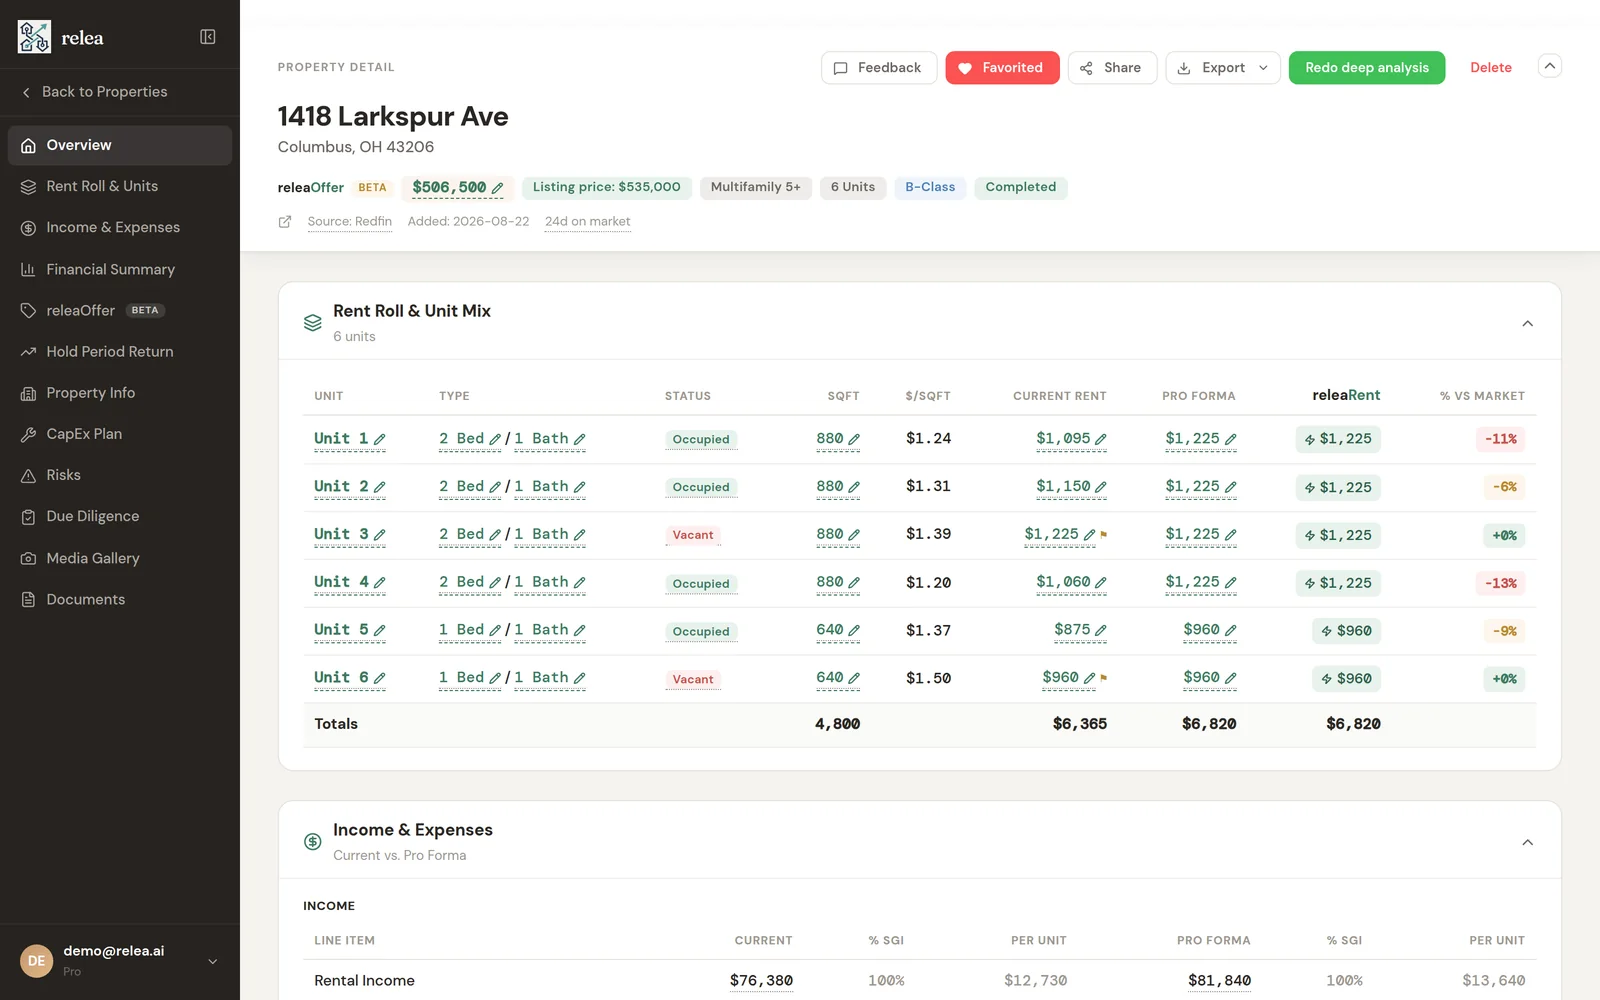
Every listing modeled in minutes, so the 45-day list is backed by numbers.
Free calculator, no account
Enter your date of sale to see your 45-day identification and 180-day exchange deadlines, and how big a replacement property to target.
Dates
Sale and replacement
Calendar days, with no roll-forward for weekends or holidays. Not tax or legal advice. Work with a qualified intermediary and a tax advisor.
45 days is very short when every property needs to be underwritten. relea underwrites a listing in minutes, with sourced rent, taxes at your purchase price and DSCR, so you can identify replacements based on the numbers.
Run it on a real listing →3 listings free. Sign up with Google or email. No card.
On a real listing
Every number on a relea listing shows its source. Built by a 20-year, multi-state operator: conservative by default, and every assumption can be overridden.
Every listing modeled in minutes, so the 45-day list is backed by numbers.
The tax bill for the replacement property resets at your purchase price. relea recalculates it.
releaOffer (beta) recommends a bid and puts a dollar figure on every adjustment.
The rules
A 1031 exchange applies when you transfer real property held for productive use in a trade or business or for investment, and receive like-kind real property held for the same purpose, as defined in the IRS Form 8824 instructions and Publication 544. A personal residence does not qualify, nor does property held primarily for sale.
There are two key deadlines. The identification period ends 45 days after the property you sold is transferred. The exchange period ends on the earlier of 180 days after the transfer or the tax return due date (including extensions) for the year of the transfer. For the sample sale date of November 20, 2026:
Since the return is due April 15, 2027, without an extension the exchange must close by April 15. With an extension, the 180-day rule applies. If April 15 falls on a weekend or holiday, the return due date shifts to the next business day, so use the override field for that year or for a fiscal-year return. The deadlines themselves do not shift for weekends or holidays; only IRS relief for federally declared disasters can postpone them.
The 45-day rule requires identifying the replacement property in writing, signed, and delivered before the 45th day ends to someone involved in the exchange (such as the qualified intermediary), with each property clearly described. The common rules: up to three properties of any value, or any number of properties if their total value does not exceed 200% of the value of the property sold, or any number if you acquire at least 95% of the value you identify.
To defer the full gain, you must buy replacement property worth at least the net sale price ($846,000 in the sample) and reinvest all of the net equity ($446,000). Any cash you do not reinvest, or debt you are relieved of that is not replaced with new debt or cash, is called boot and is taxable to the extent of the gain. In the sample, a $1,000,000 replacement property requires $554,000 of new debt.
Sources: IRS, Instructions for Form 8824, Like-Kind Exchanges, and Publication 544, Sales and Other Dispositions of Assets. This page does no tax calculation, on purpose.
Before you sell
This is for education only, not tax or legal advice. Always work with a qualified intermediary and your tax advisor on a 1031 exchange.
Questions
After your 3 free listings, pay as you go for as low as $3 per listing, or subscribe: Plus is $49 a month for 25 listings (about $1.96 per listing) and Pro is $149 a month for 150 (about $0.99 per listing). See plans
On the date the property you sold transfers. It ends at midnight on the 45th calendar day after that: for a November 20, 2026 sale, January 4, 2027.
Yes. The exchange period ends on your tax return due date, including extensions, for the year of the sale if that comes before day 180. A sale late in the year can be capped by the April 15 due date unless you extend your return, which restores the full 180 days.
No. Both periods are calendar days. If a federally declared disaster occurs, the IRS may announce relief that postpones these deadlines.
Buy replacement property worth at least the net sale price and put in all of the net equity: $846,000 and $446,000 in the sample. Any cash you keep or debt relief you don’t replace is called boot and is taxable.
No. A primary residence is not investment property for 1031 purposes. There is a separate tax exclusion for home sales; consult your tax advisor, especially for mixed-use property.
Same fourplex, next question
All of these calculators open on the same sample fourplex, so you can carry one deal from one question to the next.
Three deals free. No card. relea builds the full model with sourced rent, taxes and CapEx.
Questions? support@relea.ai. We reply within one business day.